Cash Advances vs Prepaid Cards for Field Staff
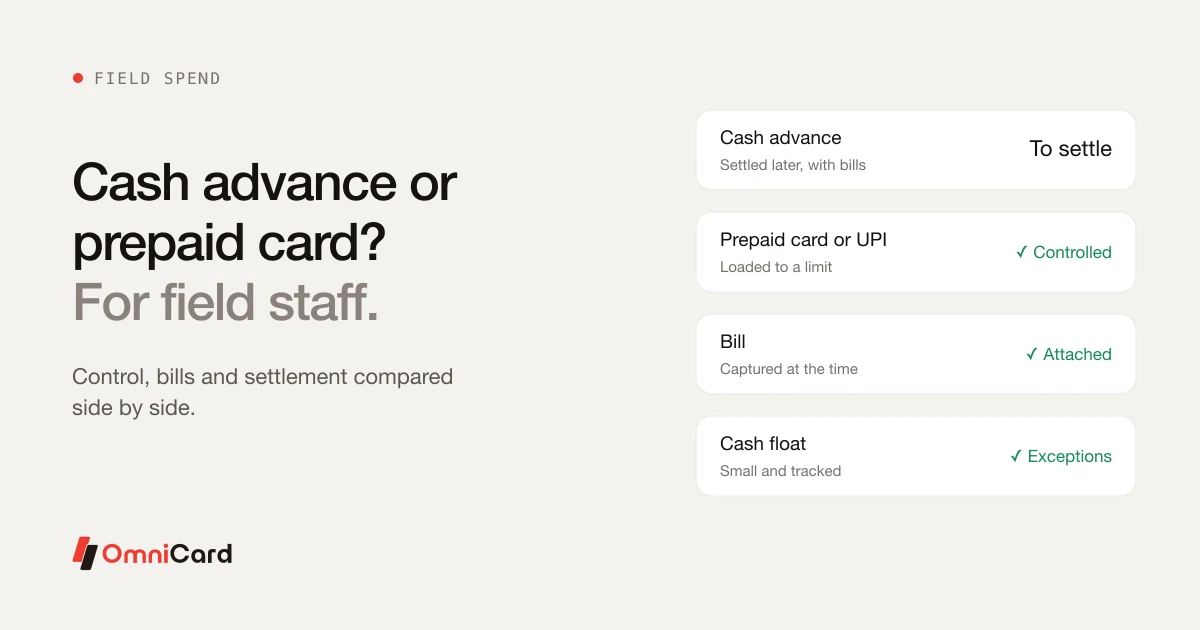
Field staff often need money before they spend it: travel, local purchases, small repairs. The two usual answers are a cash advance or a prepaid card. They behave very differently once the money is out.
Cash advance
- Simple to give
- No limit on what it is used for
- Needs settling afterwards, with bills
- Open advances build up if staff forget to settle
Prepaid card or UPI from company funds
- Money is loaded to a limit
- Spend can be restricted by category, merchant and location
- The bill is captured at the time
- Nothing to settle later
When a cash advance still makes sense
For places where cards and UPI are not accepted, or for one-off cash needs. Keep these small and settled quickly.
A mixed approach
Use cards and UPI for the bulk of field spend, and a small, tracked cash float for the exceptions.
How OmniCard fits
OmniCard staff pay by UPI (an @omni ID) or RuPay card, physical or virtual, from company funds, with limits set by employee, category, merchant, location and time. OmniCard issues prepaid instruments and does not offer credit lines. OmniCard is run by Eroute Technologies Pvt. Ltd., an RBI-authorised Prepaid Payment Instrument (PPI) issuer and a direct NPCI issuer for RuPay cards, UPI (the @omni handle) and FASTag, with no sponsor bank in between.
Related: Prepaid card for business
Keep reading
What tools can help Indian logistics firms replace cash advances to drivers with digital cards or wallets?
All you need to know about Prepaid Cards
Prepaid Card Explained: Unlocking the Benefits of Prepaid Cards
GPS-Verified Field Trips and Mileage Reimbursement
Expense Policy for Field Sales Teams