Cash, Cards, or UPI? For Business Spend, One of These Is Winning — Here's Why: OmniCard's UPI for Business
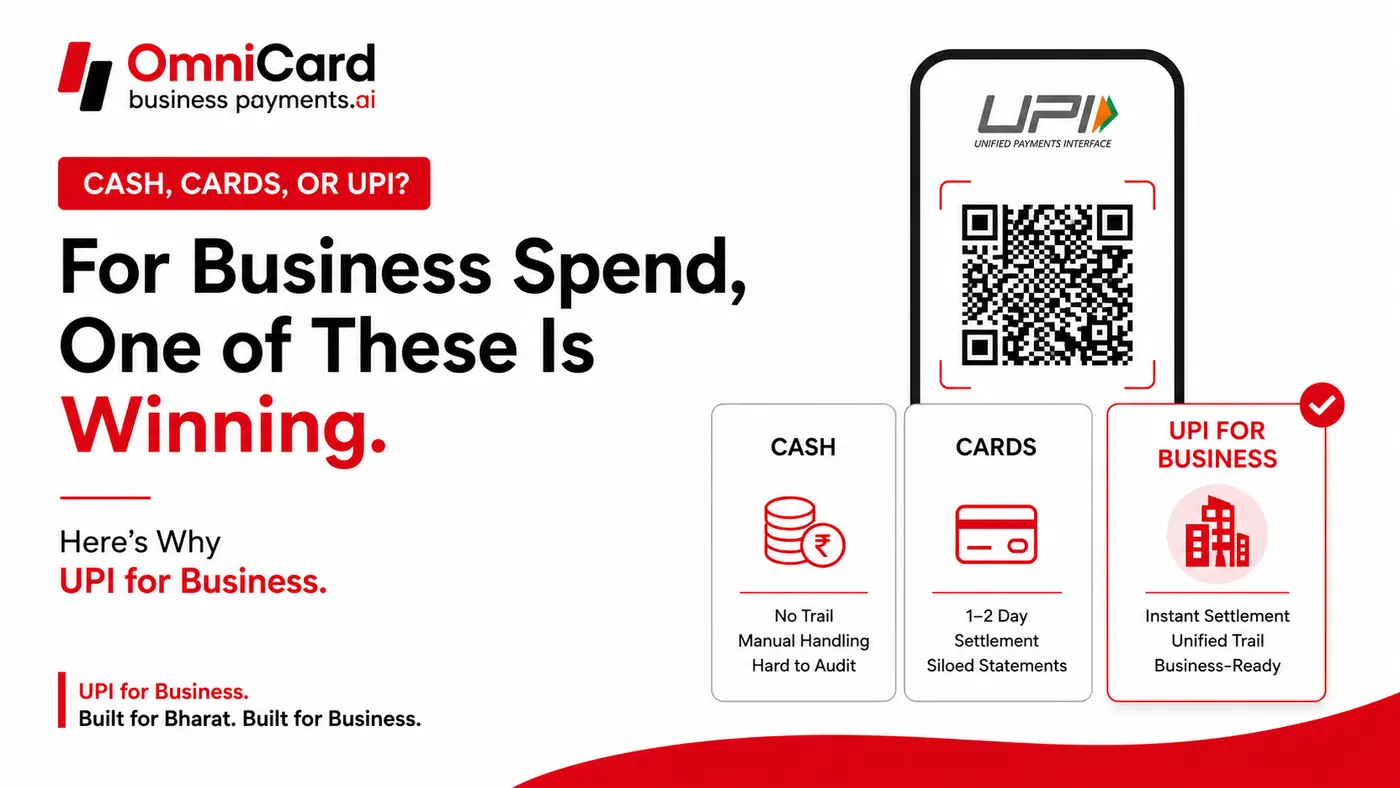
Every business runs its spend through the same three rails: cash for the small, off-the-books stuff; cards for controlled, trackable spend; and UPI for everything fast and everyday. Most finance teams have never actually compared what each one costs them in fees, time, and visibility. When you do, one rail pulls ahead by a wide margin — and it's the one businesses have historically treated as an afterthought.
That's the case for UPI for business. As part of India's Business Fintech OS, OmniCard's UPI for Business turns what's usually a personal-app habit into real payment infrastructure — spend tracking, reconciliation, and audit trails included — sitting on the same platform as RuPay prepaid cards and expense management.
Cash vs. Cards vs. UPI for Business: The Real Comparison
Line them up side by side and the differences are stark.
Cash costs nothing on paper, but it's the most expensive rail in practice — handling, storage, and shrinkage eat into it, and it leaves almost no trail. It settles instantly but has to be manually banked and reconciled. No setup is needed to spend it, which is exactly why it survives for small, off-the-books spend — and exactly why it's the hardest thing for a finance team to audit.
Cards carry a real cost — interchange and MDR typically running 1–2%+ per transaction — and settlement usually takes one to two days unless you pay extra for instant. What they're genuinely good at is large, planned, credit-backed spend: the statement trail is strong, though it stays siloed per card and per issuer rather than living in one place. Onboarding a new payee means KYC, card issuance, and underwriting — not something you do for a one-off payment.
UPI for business beats both on the metrics that matter for everyday spend. It settles instantly, 24/7, including weekends and holidays. Every payment is ID-linked, exportable, and GST-ready by default, so the trail exists automatically instead of needing to be reconstructed later. Paying a new counterparty takes minutes — just a UPI handle, no underwriting. And as of September 2025, NPCI has cleared it to carry real business ticket sizes too, with limits raised to ₹5 lakh for verified merchant categories, closing the one gap that used to push larger payments toward cards.
Cash still wins on zero setup friction. Cards still win on large, planned, credit-backed spend. But for the sheer volume of everyday business spend — reimbursements, small supplier settlements, recurring payouts, day-to-day operating expenses — UPI for business now beats both on speed and traceability, and it's the only one of the three built to be instant and fully traceable at the same time.
The Data Backs the Shift
UPI just had its biggest month ever. In July 2026, NPCI data shows the rail processed 23.66 billion transactions worth ₹29.88 lakh crore — its highest-ever monthly volume, up 22% year-on-year in volume terms. Compare that to cards: India's credit card market crossed ₹2.17 lakh crore in monthly spend at its September 2025 peak, with roughly 115 million cards in circulation nationwide — a fraction of UPI's reach, and concentrated in high-ticket, e-commerce-heavy spend rather than the everyday transactions that make up most business cash flow.
The gap shows up clearest on the merchant side. Person-to-Merchant (P2M) UPI payments hit 67.01 billion transactions in H1 2025 alone, growing 37% year-on-year — a volume no card network or cash workflow can match. And regulators are actively widening the lane for business use: NPCI raised per-transaction limits to ₹5 lakh for verified merchant categories effective September 2025, up from the old ₹1 lakh retail cap, explicitly to let UPI carry real business ticket sizes instead of just chai-and-samosa payments.
Industries Leading the UPI for Business Shift — And What's Next
The pace of adoption isn't uniform. Some industries are already running most of their spend through UPI; others are just getting started. Here's where things stand:
- Retail and e-commerce. UPI processed 22.35 billion transactions in April 2026 alone, and it's now the default rail behind checkout, not just a payment option. India's D2C segment is projected to reach $60 billion by 2030, with MSME sellers showing 53% preference for it — almost entirely UPI-first. Outlook: as quick commerce and tier-2/3 online shopping scale, UPI's share of retail business spend only grows.
- B2B trade and wholesale. India's domestic B2B e-commerce market has scaled to roughly $60 billion and is projected to reach $200 billion by 2030. What used to be NEFT- and cheque-heavy wholesale settlement is increasingly moving to UPI for faster, escrow-backed trade credit cycles. Outlook: as NPCI's higher merchant limits mature, expect UPI to keep taking share from NEFT/RTGS for mid-sized B2B spend.
- Logistics and fleet operations. Toll collections hit a record ₹70,278 crore in FY26, up 14.4% year-on-year, and from April 2026, cash was fully phased out at national highway toll plazas — FASTag and UPI are now the only accepted payment modes. For fleet-heavy businesses, this isn't optional digitization anymore; it's regulatory reality. Outlook: UPI becomes the default and reconciliation layer for every fleet's toll and fuel spend, not just an add-on.
- Government and institutional procurement. The Government e-Marketplace (GeM) crossed ₹16.41 lakh crore in cumulative GMV by November 2025, with digital, UPI-linked settlement built into the procurement flow. Outlook: as public-sector digital procurement deepens, UPI-based settlement becomes table stakes for any business spending against government contracts.
- SME manufacturing and services. Still the earliest-stage segment relative to its size — over 31% of GDP and nearly 39 crore livelihoods, per the Ministry of MSME, but still leaning on cash and informal UPI handles for business spend rather than integrated infrastructure. Outlook: this is the segment with the most ground to cover, and the one where consolidated platforms stand to add the most value.
A clarification since it comes up often: OmniCard's UPI for Business isn't a wallet or a checkout plug-in — it's business spend infrastructure layered with reconciliation and reporting, built to sit alongside RuPay prepaid cards and expense management in the same platform, not as a separate login.
How UPI for Business Actually Works as Infrastructure
The reason most businesses haven't felt this shift yet is that they're still using UPI the way a consumer does — one personal-style handle, checked manually, reconciled by hand. Business infrastructure looks different:
- Dedicated business UPI handles, not personal ones, so business spend never gets mixed up with anyone's individual account.
- Every payment auto-tagged and GST-ready the moment it's made, instead of exported and matched at month-end.
- One ledger across UPI, RuPay prepaid cards, and expense management — so a CFO sees total business spend in one place, not three.
- Audit trails by default, on RBI-licensed rails, instead of unregulated UPI handles carrying business-critical volume with no compliance layer behind them.
SMEs Are Where the Real Adoption Story Is
The myth that UPI for business is an urban, enterprise-only phenomenon doesn't hold up. PayNearby's SME Digital Index 2026, surveying 10,000 retailers and small businesses, found that UPI and Aadhaar-enabled banking together now account for 61% of transactions at semi-urban and rural SME stores — even as cash still holds 37% as the single largest individual mode. The same report found 71% of retailers now use AI tools to run daily operations, and 87% say they feel more confident with digital tools than they did a year ago.
That's the segment India's Business Fintech OS is built for: not just the top 500 enterprises, but the tens of millions of SMEs — accounting for over 31% of GDP and livelihoods for nearly 39 crore people — still choosing between cash, cards, and unmanaged UPI with no single view of any of it.
The CFO's View: Why UPI for Business Needs to Sit Inside the Finance Stack, Not Beside It
For a finance controller, the ROI of UPI for business isn't the payment itself — UPI is already fast and instant. The ROI is what happens around the payment:
- One reconciliation trail, not three. UPI spend and card spend hitting the same ledger means finance stops manually matching reference numbers against bank statements.
- Real-time visibility on spend. Knowing what's gone out — and where — the moment it happens, instead of at month-end.
- GST-ready records by default. Every UPI payment tagged, categorized, and export-ready, cutting days off month-end close.
- Audit-grade compliance. RBI-licensed infrastructure with built-in trails, instead of unregulated UPI handles doing business-critical volume.
The Bigger Shift: From "Accepting UPI" to "Running the Business on UPI"
For years, the conversation around UPI for business was about acceptance — putting a QR code at the counter, alongside cash and card machines as just another option. The next phase is about replacement — UPI overtaking cash and cards for the bulk of everyday business spend, not because it's the newest rail, but because it's the only one that's instant and fully traceable at once.
That's the shift OmniCard is building toward: not another UPI handle to manage, but the layer that makes UPI for business actually work like business infrastructure.
Looking to move business spend onto one reconciled platform instead of a patchwork of cash, cards, and UPI apps? Explore how OmniCard's UPI for Business fits your business.
Data sources: National Payments Corporation of India (NPCI) monthly UPI statistics (April–July 2026), Press Information Bureau release on UPI@10 (April 2026), PayNearby SME Digital Index Report 2026, Ministry of MSME's 2025-26 fact-sheet, IBEF industry reports on e-commerce, retail, and B2B commerce (2026), National Highways Authority of India / Ministry of Road Transport toll and FASTag data (FY26), Government e-Marketplace (GeM) procurement data (November 2025), Business Standard credit card spending data (2025-26), and RBI/NPCI circulars on UPI authentication and merchant transaction limits (2025-26).