Petty Cash Book: Meaning, Format, Example and Advantages
A petty cash book is a subsidiary book in which a business records small, day-to-day cash payments such as stationery, courier, local travel and tea for visitors. It is kept by a petty cashier, usually under the imprest system, and it works as both a book of original entry and a ledger account for petty cash. Below you will find the format, a worked example, the reconciliation process and the advantages and limits of keeping one.
Running petty cash across branches? OmniCard replaces cash boxes with UPI and RuPay prepaid cards, with limits per store and a record of every spend. See petty cash management →
What is petty cash?
Petty cash is a small amount of cash a business keeps on hand to pay for minor expenses. It saves the effort of raising a purchase order, a cheque or a bank transfer for a ₹200 courier or a ₹150 auto fare. The fund is small, but it moves often, so it needs its own record.
What is a petty cash book?
A petty cash book is the ledger that tracks that fund. Every payment out of it is written in with the date, a voucher number, what it was for and the amount. Every top-up from the main cashier is written in as a receipt. At any point, the cash in the box plus the vouchers paid should equal the fund you started with.
Petty cash book in accounting
In accounting, the petty cash book is a subsidiary book. Businesses keep it so that the main cash book is not filled with dozens of small entries.
- It is a book of original entry. Small payments are first recorded here, supported by petty cash vouchers.
- It is also a ledger account. The balance in the petty cash book is the balance of the petty cash account, so a separate petty cash ledger is not needed.
- Only totals reach the ledger. In an analytical petty cash book, each expense column (postage, stationery, conveyance and so on) is totalled for the period and posted to the matching ledger account in one entry.
- It is usually kept on the imprest system. The petty cashier gets a fixed float, and the main cashier reimburses exactly what was spent at the end of each period.
Petty cash book format
There are two common formats. Use the simple format if you have only a handful of payments a month. Use the analytical (columnar) format when you want expenses sorted by head as you go.
Simple petty cash book format
| Date | Voucher no. | Particulars | Receipts (₹) | Payments (₹) | Balance (₹) |
|---|---|---|---|---|---|
| 1 Sep | Cash received from main cashier | 5,000 | 5,000 | ||
| 2 Sep | 1 | Printer paper and pens | 450 | 4,550 | |
| 4 Sep | 2 | Courier to client | 220 | 4,330 |
Analytical petty cash book format
The analytical petty cash book has a receipts column on the left, a total payments column, and one column for each type of expense. This is the format most accounting courses and most finance teams use.
| Receipts (₹) | Date | V. no. | Particulars | Total (₹) | Postage | Stationery | Conveyance | Refreshments | Repairs |
|---|---|---|---|---|---|---|---|---|---|
| 5,000 | 1 Sep | To cash (imprest) | |||||||
| 2 Sep | 1 | By printer paper and pens | 450 | 450 | |||||
| 4 Sep | 2 | By courier to client | 220 | 220 | |||||
| 5 Sep | 3 | By taxi to bank | 380 | 380 | |||||
| 8 Sep | 4 | By tea and snacks, client meeting | 300 | 300 | |||||
| 10 Sep | 5 | By fan repair | 650 | 650 | |||||
| Total payments | 2,000 | 220 | 450 | 380 | 300 | 650 | |||
| 30 Sep | By balance c/d | 3,000 | |||||||
| 5,000 | 5,000 | ||||||||
| 3,000 | 1 Oct | To balance b/d | |||||||
| 2,000 | 1 Oct | To cash (reimbursement) |
Petty cash book example: the imprest system step by step
Using the table above:
- Set the imprest. On 1 September the main cashier gives the petty cashier ₹5,000. This is the fixed float.
- Pay and record. Each payment is made against a signed voucher with the bill attached, and entered in the total column and in its expense column.
- Total the columns. At month-end, payments total ₹2,000: postage ₹220, stationery ₹450, conveyance ₹380, refreshments ₹300 and repairs ₹650.
- Balance the book. ₹5,000 received less ₹2,000 paid leaves ₹3,000, carried down as the closing balance.
- Reimburse. The main cashier pays ₹2,000 on 1 October, which brings the float back to ₹5,000.
- Post to the ledger. Each column total is debited to its expense account (Postage A/c ₹220, Stationery A/c ₹450 and so on) and the petty cash account is credited with ₹2,000. The reimbursement is recorded as Petty Cash A/c Dr ₹2,000 to Bank or Cash A/c ₹2,000.
Types of petty cash
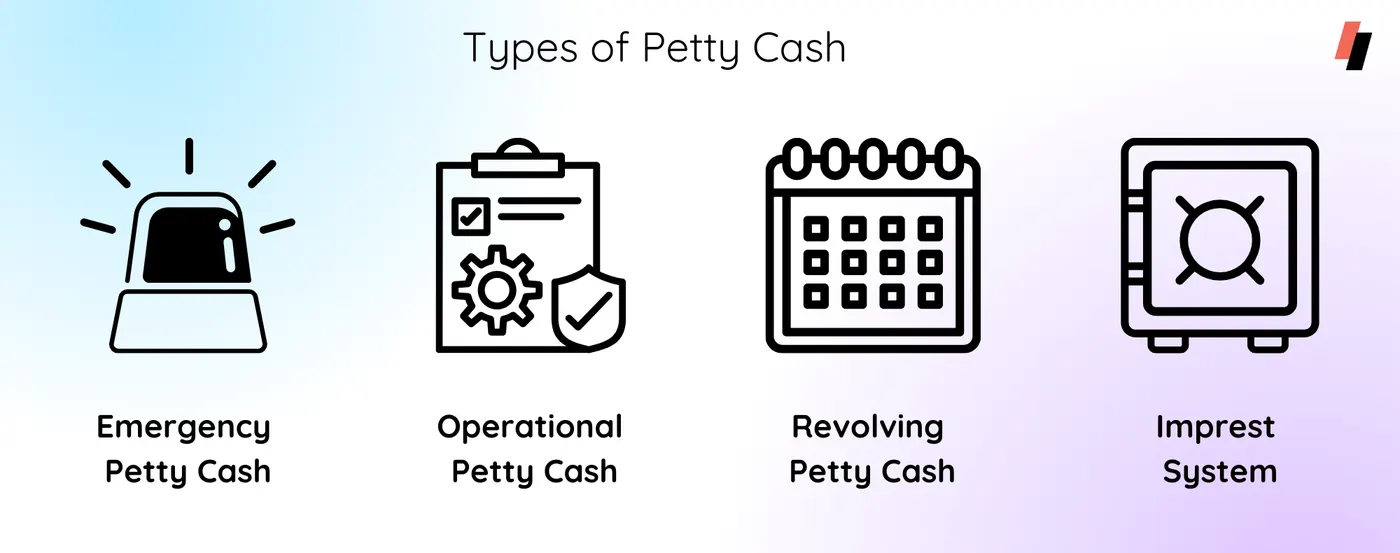
Operational petty cash
The most common type, used for everyday costs such as office supplies, minor repairs, local travel and staff meals. It keeps work moving without a formal reimbursement claim for every small bill.
Emergency petty cash
A separate fund for sudden needs, such as an equipment breakdown or an urgent supply run. Keeping it apart from the operational float means one does not drain the other.
Revolving petty cash
A fund that is topped up at regular intervals, usually monthly, so the balance stays roughly constant.
Imprest system
The fund is held at a fixed amount. When it runs low, it is topped up by exactly the amount spent. Because cash plus vouchers must always equal the imprest, this is the easiest system to check and audit, and it is the one most businesses use for their petty cash book.
Examples of petty cash expenses
- Office supplies: pens, notepads, printer paper, other stationery.
- Refreshments: tea, coffee or snacks for staff and visitors.
- Local travel: auto, taxi or bus fares for short work trips.
- Postage and courier: letters, documents and small parcels.
- Repairs and maintenance: a plumber, an electrician, a fan or lock repair.
- Small team events: a birthday cake or a small team lunch.
Advantages of a petty cash book
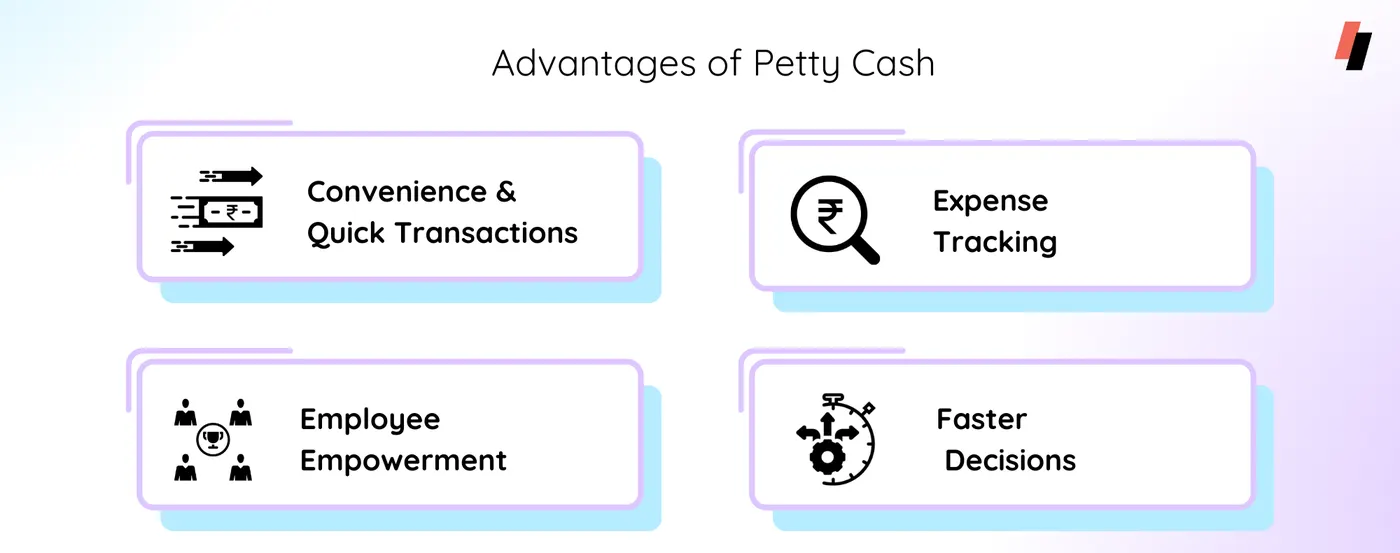
- Saves the main cashier's time. Small payments are handled separately, so the main cash book records one reimbursement instead of dozens of entries.
- Controls small spending. Under the imprest system, the petty cashier can never spend more than the float without asking for a top-up.
- Easy to check at any time. Cash in hand plus vouchers paid should equal the imprest amount, so a surprise count shows problems quickly.
- Simpler ledger posting. The analytical format totals each expense head, so only one entry per head goes to the ledger each period.
- Clear record for audit. Each payment has a voucher number, a date, a purpose and a bill.
- Faster day-to-day decisions. Staff can pay for small, urgent needs without waiting for a formal approval.
Disadvantages and challenges of petty cash
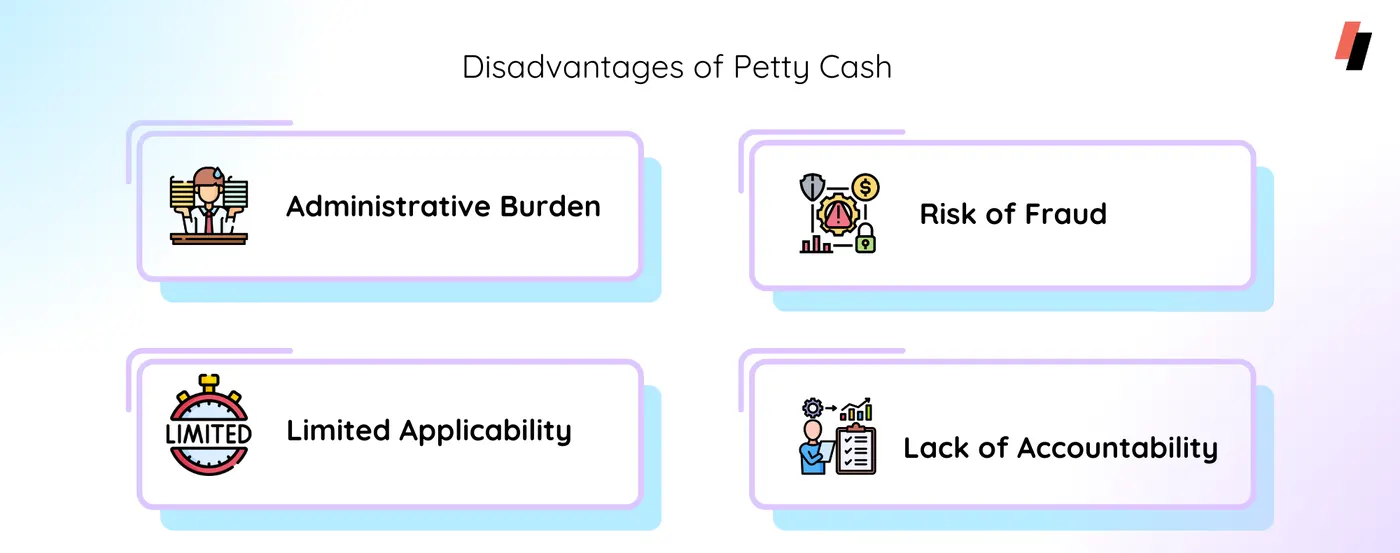
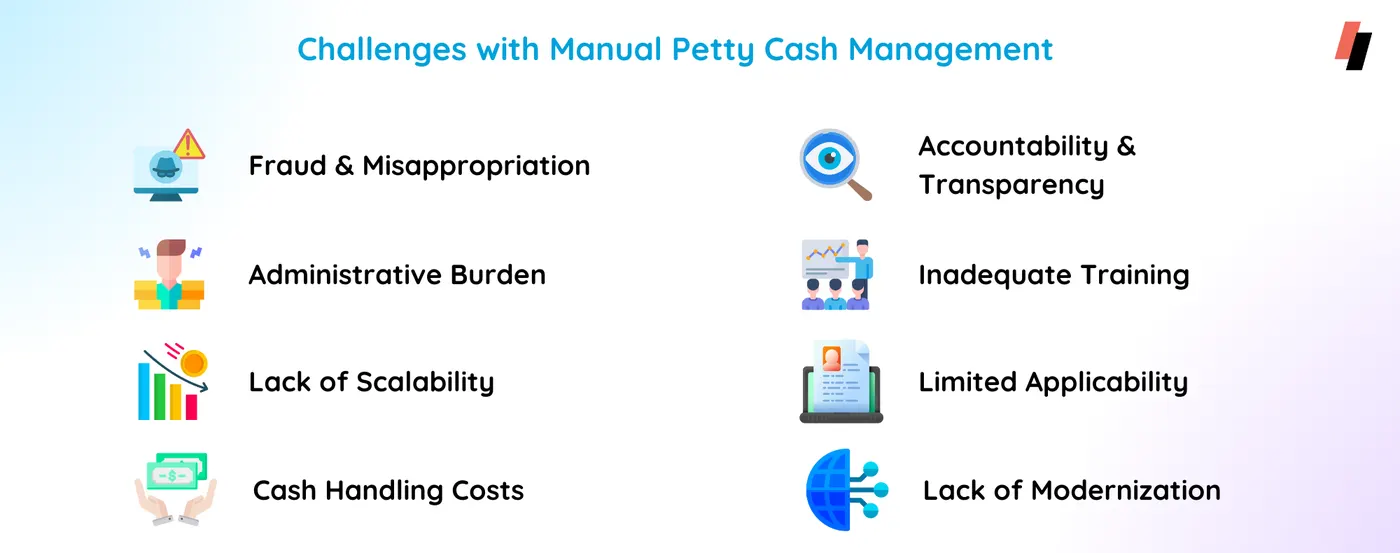
- Weak accountability. Petty cash is informal by nature. Without vouchers and regular counts, money can go missing and records drift from reality.
- Risk of fraud. Fake bills, inflated amounts and cash taken without a voucher are the most common problems.
- Administrative work. Topping up the fund, writing entries and reconciling take time, which grows with every branch.
- Only suits small payments. Larger or unusual costs still need a formal purchase and approval process.
- Cash handling costs. Cash needs a safe, a custodian and sometimes insurance, and it can be lost or stolen.
- Hard to scale. Ten branches mean ten cash boxes, ten books and ten reconciliations, with finance seeing the numbers only after month-end.
- Training gaps. Custodians who are not trained in record-keeping make errors that surface only at audit.
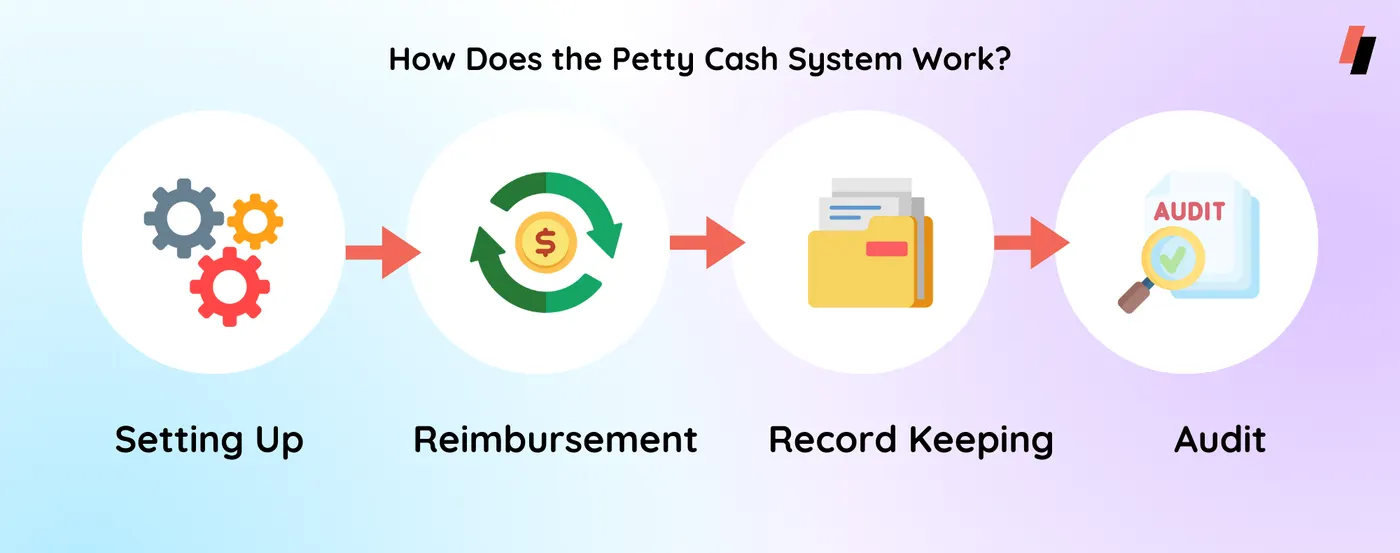
How the petty cash system works
- Set up the fund. Decide the float amount based on typical monthly spend and name a custodian (and a backup).
- Record every payment. Enter the date, voucher number, purpose, amount and the person paid, with the bill attached.
- Replenish. When the fund runs low or at month-end, the custodian submits the vouchers and gets the amount spent reimbursed.
- Audit. Check transactions regularly for accuracy, genuine bills and policy compliance.
Best practices for managing a petty cash book
- Secure storage: keep cash in a locked box or safe.
- Limited access: only the custodian and a named backup handle the fund.
- Receipts for everything: no bill, no payment.
- Regular reconciliation: count and reconcile at least monthly, and do surprise counts.
- Training: teach custodians how to fill vouchers, write entries and balance the book.
Petty cash reconciliation process
Reconciliation proves that the petty cash book, the vouchers and the cash in the box agree. Follow these steps at every replenishment and at month-end:
- Count the cash in the box, note by note.
- Total the vouchers and bills paid since the last reconciliation.
- Check the equation. Cash in hand plus total vouchers should equal the imprest amount.
- Match to the book. The payments total in the petty cash book should equal the vouchers total, and the book's closing balance should equal the cash counted.
- Investigate any difference. Look for missing bills, arithmetic errors and unrecorded top-ups. Record any unexplained gap in a cash short and over account and report it.
- Sign off and replenish. The custodian and a reviewer sign the reconciliation, and the main cashier tops the fund back up to the imprest.
Role and responsibilities of the petty cashier
The petty cashier is the person responsible for the petty cash fund. The amounts are small, but the job needs care:
- Custodian of the fund: keeps the float safe and makes sure it matches the book.
- Recording transactions: writes every payment in the petty cash book with a voucher and bill.
- Handling reimbursements: checks small out-of-pocket claims from staff against policy before paying them.
- Reconciliation: counts and reconciles the fund regularly and investigates any gap.
- Reporting: submits the book and vouchers to the finance team for replenishment and posting.
Why businesses are moving away from the manual petty cash book
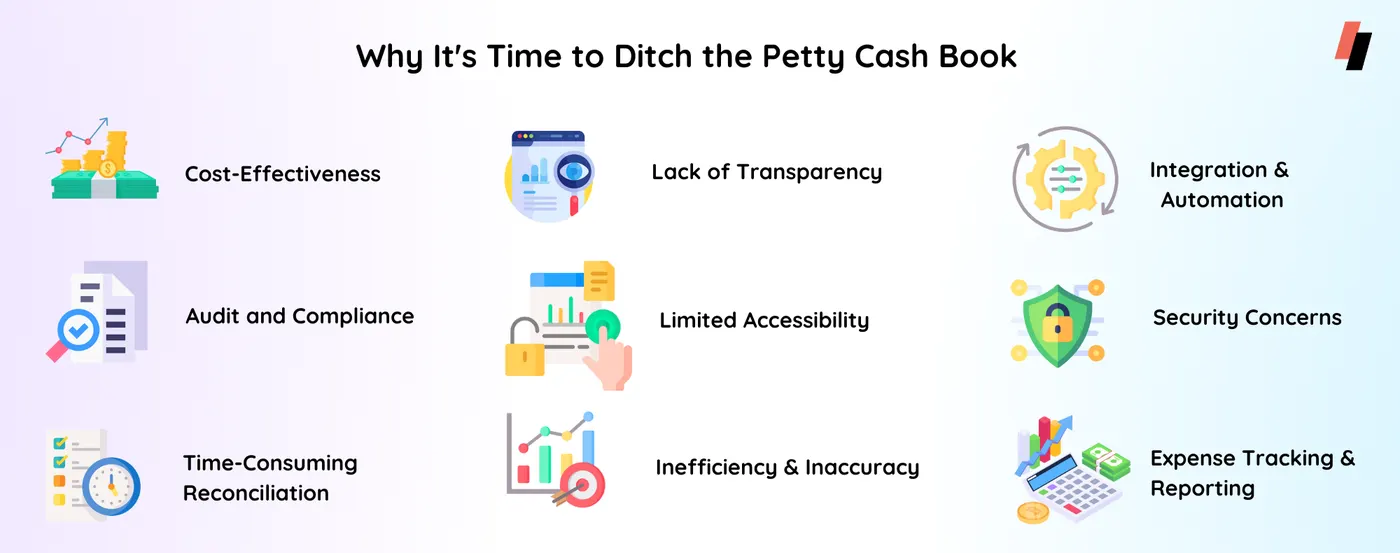
A paper petty cash book works for one office. It gets harder as the number of branches, stores or field staff grows.
- Errors: manual entries and arithmetic mistakes are common, and checking them takes time.
- Limited access: the book sits in one place, so finance cannot see balances or spend until it is sent in.
- Low transparency: it is hard to see who spent what, where and when across locations.
- Slow reconciliation: each branch's book has to be matched to vouchers by hand.
- Security: paper records and cash boxes can be lost, damaged or stolen.
- Weak reporting: spend by category, branch or month needs manual re-keying into spreadsheets.
- Audit effort: pulling bills and vouchers for auditors is slow.
- Duplicate entry: the same expense is written in the book and then keyed into the accounting system.
Petty cash in 2026
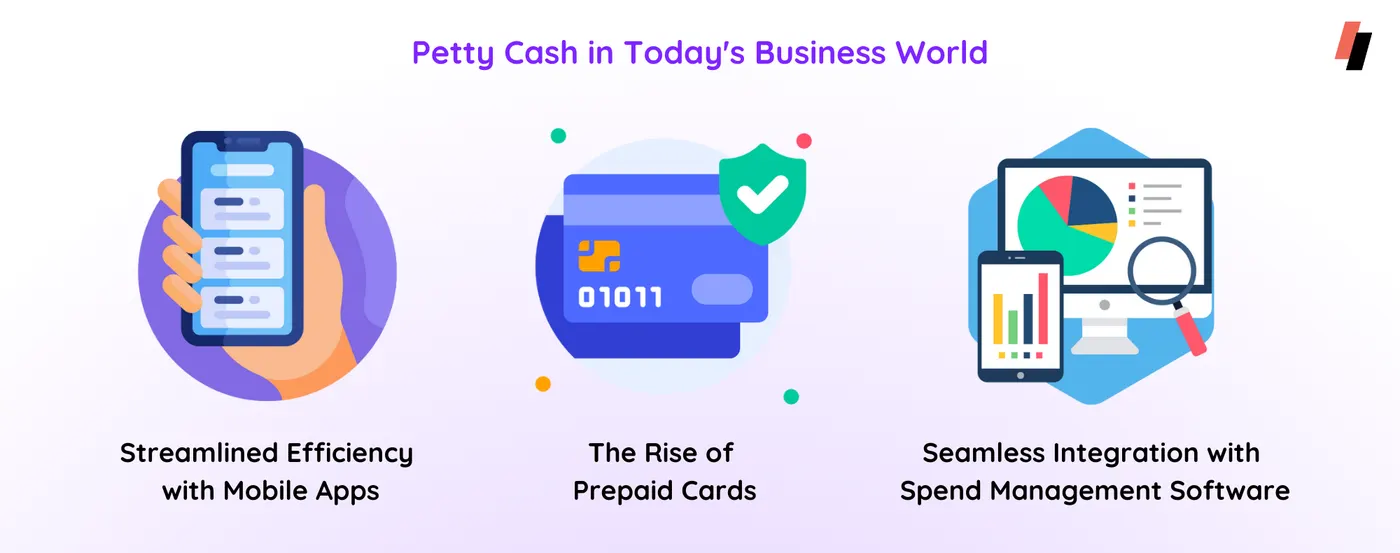
Most small payments in India are now made by UPI or card, so petty cash no longer has to mean physical cash:
- Mobile apps: staff record the expense and photograph the bill at the point of purchase, instead of filling paper vouchers.
- Prepaid cards and UPI: employees get a prepaid card or a UPI ID loaded with company funds and a spending limit, so there is no cash float to count.
- Spend management software: payments, bills, approvals and reports sit in one place, and entries flow to the accounting system.
Why go digital?
Accuracy and accountability
Each payment is recorded when it happens, with the bill attached, so there are fewer lost receipts and missing entries.
Real-time monitoring
Digital petty cash management shows balances, recent transactions and spend by category as they happen, so finance does not have to wait for month-end.
Security and fraud prevention
There is less physical cash to lose or misuse, and access controls limit who can spend and approve.
Faster approvals
Approval workflows replace chasing signatures on paper vouchers.
Paperless records
Employees photograph bills on their phones instead of keeping paper receipts in a drawer.
Integration with accounting
Entries flow to the accounting system, so the reconciliation is quicker and nothing is keyed in twice.
Petty cash with OmniCard
OmniCard runs petty cash on the same platform as corporate cards, business UPI, reimbursements and bill payments. Instead of a cash float, each store, branch or employee pays from company funds by an @omni UPI ID or an OmniCard RuPay prepaid card. Limits by employee, category, merchant, location and time are checked before the payment goes through. The bill is captured by receipt OCR, and entries post to ERP and accounting systems such as Tally, SAP, Oracle, Zoho and Microsoft Dynamics. See petty cash management and spend management.
Frequently asked questions
What is a petty cash book in simple words?
It is a small cash book for small payments. The petty cashier writes down each minor expense, such as courier, stationery or local travel, with a voucher and a bill, and gets the amount spent reimbursed by the main cashier.
Is a petty cash book a journal or a ledger?
Both. It is a book of original entry, because small payments are first recorded in it, and it is a ledger account, because its balance is the balance of the petty cash account.
What is the format of an analytical petty cash book?
It has a receipts column, then date, voucher number, particulars and total payments, followed by one column for each expense head such as postage, stationery, conveyance and refreshments. Each column is totalled at the end of the period and posted to its ledger account.
What is the imprest system of petty cash?
The petty cashier gets a fixed amount, called the imprest. At the end of each period the main cashier pays back exactly what was spent, so the fund returns to the same amount every time.
How often should petty cash be reconciled?
At least at every replenishment and at month-end. Surprise counts in between help catch problems early.
Can petty cash be managed without cash?
Yes. Many businesses now give staff prepaid cards or UPI IDs loaded with company funds and a spending limit, so each payment is recorded electronically and there is no cash box to count.